Indian businesses and individuals are increasingly investing in overseas companies to expand their operations, enter international markets, and build global business relationships. However, making an investment outside India involves certain foreign exchange regulations.
The ODI rules in India explain how Indian residents can invest in foreign businesses, report transactions, maintain records, and exit overseas investments.
The main regulatory framework includes the Foreign Exchange Management Act (FEMA), Foreign Exchange Management (Overseas Investment) Rules, 2022, Overseas Investment Regulations, 2022, and RBI directions.
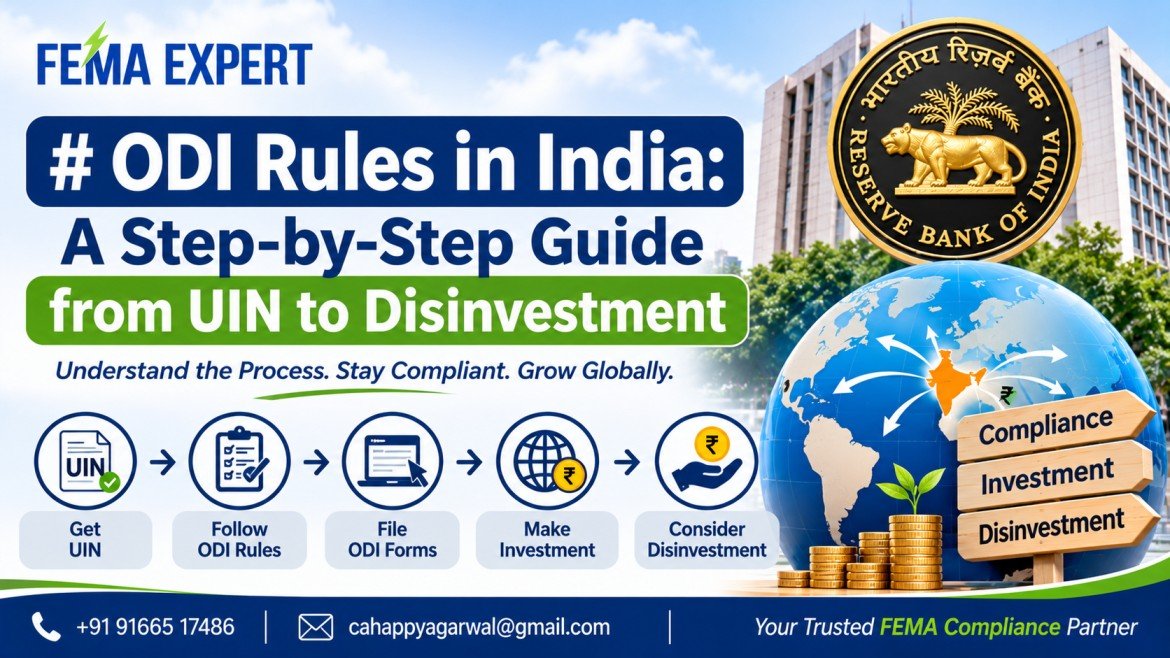
This guide explains the overseas direct investment rules in simple terms, from the initial application and UIN allotment to annual reporting and disinvestment.
Overseas Direct Investment (ODI) means certain investments made by Indian residents in foreign entities.
An investment generally qualifies as ODI when an Indian resident:
Once an investment is classified as ODI, it generally continues to be treated as ODI even if the holding later falls below 10%.
The ODI regulations apply to persons resident in India making eligible overseas investments.
This includes:
The applicable conditions differ depending on the investor’s legal structure and the nature of the investment.
Overseas investment can generally be made under the automatic route, subject to prescribed conditions. Certain transactions require prior government or RBI approval.
Automatic Route: Eligible investors can proceed without obtaining specific prior approval, provided they satisfy the applicable ODI conditions.
Approval Route: Prior approval may be required for certain restricted sectors, specified jurisdictions, or transactions covered by the approval provisions.
For example, financial commitment exceeding USD 1 billion in a financial year requires prior RBI approval, even if it falls within the investor’s overall financial commitment limit.
The first practical step is to approach an Authorised Dealer (AD) Category-I bank.
The AD bank reviews the proposed transaction and checks whether it meets the applicable FEMA requirements.
The investor generally needs to:
The initial investment remittance must follow the applicable reporting and UIN requirements.
A Unique Identification Number (UIN) is allotted to a foreign entity for recording and tracking its overseas investment details.
The investor submits Form FC and supporting documents through the designated AD bank. The bank verifies the information and reports the transaction through the RBI’s Overseas Investment system.
Once the UIN is allotted, the bank can facilitate the eligible remittance.
Important: A UIN is not an RBI approval or confirmation that every aspect of the investment is legally permitted. It is an identification number used for regulatory records.
The applicable investment limit depends on the investor’s category.
Investors should calculate their available limit before entering into an overseas investment transaction.
The overseas investment framework restricts investments in certain activities and structures.
Restrictions cover activities such as gambling and certain prohibited financial products linked to the Indian rupee. Investments in prohibited jurisdictions and certain structures involving excessive subsidiary layers are also restricted.
Resident individuals have additional conditions. For example, an individual who makes ODI without control cannot acquire control in a foreign entity if that entity subsequently establishes or acquires a subsidiary or step-down subsidiary.
Therefore, investors should review the foreign company’s business activities, ownership structure, and control arrangements before investing.
Following the correct timeline is an important part of ODI compliance.
| Compliance activity | Applicable timeline |
|---|---|
| Form FC and UIN | Before making the initial ODI remittance |
| Evidence of investment | Within 6 months of making the investment |
| Annual Performance Report (APR) | Generally within 60 days from the foreign entity’s accounting year-end |
| FLA Return | Generally by 15 July, where applicable |
| Late reporting | Regularisation through the prescribed LSF process, where available |
The exact reporting requirement depends on the transaction and investor category.
ODI compliance does not end after the money is transferred overseas. Investors must also complete applicable post-investment reporting.
Evidence of Investment: The investor must submit documents proving the acquisition of foreign equity capital within six months. These may include share certificates or other permitted evidence.
Annual Performance Report (APR): The APR provides information about the financial and operational performance of the foreign entity. It must be submitted where required under the applicable rules.
FLA Return: Eligible Indian entities with outstanding foreign assets or liabilities arising from FDI or ODI may need to submit the annual Foreign Liabilities and Assets (FLA) Return to RBI.
Maintaining these records helps businesses monitor their overseas investments and meet reporting obligations.
Disinvestment means selling, transferring, or otherwise exiting an overseas investment.
An Indian investor must follow the applicable FEMA conditions before completing the exit.
Important requirements include:
Additional conditions may apply where the foreign entity is being liquidated or the investment is being transferred to another person.
Missing an ODI reporting deadline can create compliance problems. However, certain delayed filings may be regularised through a Late Submission Fee (LSF) under the applicable framework.
The RBI-prescribed calculation generally includes:
The calculation depends on the reporting category and delay period. The LSF option is generally available up to three years from the original due date.
Failure to follow the overseas investment regulations can lead to regulatory action under FEMA.
Possible consequences include:
Investors can use this simple checklist to manage their overseas investments.
Before investment:
During investment:
After investment:
Some common mistakes made by investors include:
A planned compliance process can help prevent these issues.
FEMA Expert provides professional guidance to Indian companies, LLPs, and individuals planning overseas investments.
Our services include:
Led by CA Happy Agarwal, FEMA Expert assists businesses with FEMA advisory, overseas investment planning, and regulatory compliance.
Understanding the ODI rules in India is important before investing in a foreign company. Investors must check their eligibility, follow the correct investment route, obtain a UIN, and complete the required reporting.
Annual compliance and proper disinvestment procedures are equally important. Taking professional guidance from an experienced ODI consultant in India can help businesses manage overseas investments and reduce regulatory risks.
1. What are ODI rules in India?
ODI rules govern how Indian residents can invest in foreign entities. They cover investment eligibility, financial commitment limits, reporting, annual compliance, and disinvestment.
2. What is a UIN in overseas investment?
A UIN is a Unique Identification Number allotted to a foreign entity for recording its overseas investment details with RBI.
3. What is the ODI limit for an Indian company?
An eligible Indian entity can generally make financial commitments up to 400% of its net worth, subject to the applicable conditions.
4. Is APR filing mandatory for ODI?
APR filing is required in applicable cases under the Overseas Investment Regulations. The reporting requirement depends on the investment structure and prescribed exemptions.
5. What happens if ODI reporting is delayed?
Eligible delayed reporting may be regularised by paying the prescribed Late Submission Fee through the designated AD bank. Other regulatory action may apply if the delay is not regularised.
6. Can an Indian company sell its overseas investment?
Yes. An Indian company can disinvest from an overseas entity, subject to applicable FEMA conditions, documentation, repatriation, and reporting requirements.